Calculate your net take-home pay from gross, gross from net, and total employer costs in Poland. Current ZUS rates, PIT income tax brackets, and mandatory minimum hourly rate.
Calculation Parameters
PLN
100 PLN30,000 PLN
32% after exceeding PLN 120,000 annual income
%
Salary Calculation Results
Net Salary (Take-Home Pay)
—
👤 Contractor Deductions (Taken from Gross)
Gross Contract Salary—
Old-age Pension contribution (9.76%)—
Disability Pension contribution (1.50%)—
Sickness insurance (2.45%)—
Total Employee Social Security (ZUS)—
Health Insurance Assessment Base—
National Health Insurance (9.00%)—
Tax-Deductible Costs (KUP)—
Tax Assessment Base—
Advance Income Tax (PIT)—
💰 Net Salary (Take-Home Pay)—
🏢 Employer Additional Contributions
Gross Contract Salary—
Employer Pension contribution (9.76%)—
Employer Disability contribution (6.50%)—
Accident insurance—
Labor Fund - FP (2.45%)—
Guaranteed Benefits - FGŚP (0.10%)—
📊 Total Employer Cost—
Salary Calculation Results
—take-home
Enter amount and calculate
Results will appear here after clicking 'Calculate Salary'
Calculate Mandate Contract Salary in Poland
The 2026 Mandate Contract (Umowa Zlecenie) Calculator is a specialized financial tool that accurately converts gross earnings to net take-home pay and net to gross under current Polish labor and tax legislation.
It accounts for mandatory ZUS social security, compulsory 9% health insurance, tax-deductible expenses (20% or 50%), PIT tax scales (12% and 32%), and the complete tax exemption for students and youth under 26 (PIT-0 for youth).
Simply enter your contractual amount or hourly rate, choose your student/employment status, and inspect the precise financial breakdown.
💰
Gross
5 000 zł
− ZUS social security
🏛️
ZUS Social
− 685,50 zł
− 9% health ins.
🏥
Health Ins.
− 388,31 zł
− advance PIT
📋
PIT Tax
− 114 zł
= net payout
✅
Net
3 812,19 zł
Gross vs Net & Employer Costs for Umowa Zlecenie
Gross pay represents the amount specified in your contract, while net pay is the actual cash deposited into your bank account after mandatory contributions and tax withholdings.
Below is a comparative breakdown of net take-home amounts across key wage levels in Poland for 2026:
3 000 PLN (gross)
2 287 PLN
5 000 PLN (gross)
3 812 PLN
10 000 PLN (gross)
7 623 PLN
Net ZUS Contributions Health + PIT
Social Security & Tax Rates on Mandate Contracts
Understanding individual contributions empowers workers and hiring companies to budget accurately in 2026.
Old-Age Pension (9.76%): Split equally: 9.76% paid by contractor and 9.76% covered by principal employer to build your future state pension.
Disability Pension (1.50%): 1.50% paid by the contractor and 6.50% financed by the employer. Secures financial disability protections.
Sickness Insurance (2.45%): Voluntary for mandate contractors, 100% paid by the contractor. Grants entitlement to paid sick leave and maternity benefits.
Health Insurance (9.00%): Mandatory for all workers except students under 26. Grants free access to the Polish National Health Service (NFZ).
Advance Income Tax PIT (12% / 32%): Assessed on taxable base after deducting ZUS and deductible costs. General tax-free allowance is PLN 30,000.
76%Net (Take-Home)
Hourly Rate & Mandatory Minimums in Poland
In 2026, the statutory minimum hourly rate for mandate contracts in Poland is PLN 31.40 gross per hour (approx. PLN 23.92 net).
Principals are legally mandated to keep accurate records of contractor hours and ensure compensation never falls below the national threshold.
Key Legal Rules Governing Hourly Rates:
Mandatory confirmation of performed hours in writing or electronically each month.
Contractors cannot waive their legal entitlement to the statutory minimum rate.
Remuneration must be disbursed at least once a month for contracts lasting over 30 days.
For registered students under 26 years, the gross PLN 31.40 rate is 100% equal to net take-home pay.
Hourly Rate Calculation Tool
PLN/h
31.40 PLN150 PLN
h
Gross Contract Salary5 024,00 PLN
Total Employee Social Security (ZUS)− 1 078,12 PLN
Advance Income Tax (PIT)− 117 PLN
Net Salary (Take-Home Pay)3 828,88 PLN
Net Earnings by Hours Worked (2026)
Calculate your monthly take-home earnings based on hours worked at the minimum rate of 31.40 PLN/h:
HoursGrossNetEmployer Cost
40 h1 256,00 PLN1 088,43 PLN1 512,98 PLN
80 h2 512,00 PLN1 975,48 PLN3 025,95 PLN
120 h3 768,00 PLN2 890,56 PLN4 538,93 PLN
160 h5 024,00 PLN3 828,88 PLN6 051,91 PLN
Calculated at statutory minimum 31.40 PLN/h gross, standard profile, 20% KUP, 12% PIT, with voluntary sickness insurance.
Practical Settlement Examples for 2026
Real-world calculation breakdowns for the 4 most common contractor situations in Poland:
Standard Contractor: PLN 5,000 gross, 20% KUP, 12% PIT
Full ZUS and voluntary sickness insurance applied. Net pay after ZUS, NFZ, and PIT with PIT-2 is PLN 3,812.19.
Exempt from social security contributions. Only 9% NFZ health insurance and 12% PIT are deducted.
Gross Contract Salary3 000,00 PLN
Total Employee Social Security (ZUS)0.00 PLN (job ≥ PLN 4,806)
National Health Insurance (9.00%) (9%)− 270,00 PLN
Tax-Deductible Costs (KUP) (20%)600,00 PLN
Advance Income Tax (PIT) (12%)− 288,00 PLN
Net Salary (Take-Home Pay)2 442,00 PLN
Step-by-Step Salary Calculation Method
How gross remuneration is converted into net take-home salary in 4 straightforward steps:
1
Step 1: Deduct ZUS Social Security
Old-age pension (9.76%), disability (1.50%), and optional sickness (2.45%) are subtracted from gross amount (total 13.71%).
− 13,71% ZUS
2
Step 2: Calculate 9% Health Insurance
Assessed on gross minus ZUS social security. Health insurance (9%) is compulsory and non-deductible from tax.
− 9% NFZ
3
Step 3: Determine Tax-Deductible Expenses (KUP)
Standard KUP is 20% (or 50% for copyright works) applied to the base income after social deductions.
KUP 20% / 50%
4
Step 4: Compute Advance Income Tax (PIT)
Tax rate (12% or 32%) is applied to taxable income, reduced by PIT-2 credit (PLN 300), producing the final net salary.
= Netto
Total Cost of Hiring for the Principal (Employer)
For Polish employers and principals, the total cost of hiring a contractor on Umowa Zlecenie exceeds gross salary due to statutory employer contributions for pension, disability, accident, and government labor funds.
Employer contributions add approximately 20.48% on top of the contractor's gross wage for standard contracts.
How is net pay calculated on a Polish Mandate Contract (Umowa Zlecenie)?
Salary is calculated in 4 steps: subtract employee ZUS social contributions (pension 9.76%, disability 1.50%, sickness 2.45%), calculate 9% health insurance, subtract 20% or 50% tax-deductible expenses (KUP), and assess 12% or 32% PIT advance minus PIT-2 allowance.
What is the difference between gross and net salary in Poland?
Gross amount is the full contractual figure agreed with the company. Net amount is the actual take-home money transferred to your bank account. The difference ranges from 0% (students under 26) to approximately 24-30% for standard adult contractors.
Is income tax (PIT) withheld from mandate contracts?
Yes, advance PIT is deducted at 12% up to PLN 120,000 annual income, and 32% above that. However, pupils and university students under 26 enjoy 0% PIT relief up to PLN 85,528 annually.
How does the number of worked hours affect the final payout?
Mandate contracts are calculated by multiplying hours worked by the agreed hourly rate. At the 2026 statutory minimum of 31.40 PLN/h: 40h = PLN 1,256 gross, 80h = PLN 2,512 gross, and 160h = PLN 5,024 gross.
What is the mandatory minimum hourly rate in Poland in 2026?
The statutory minimum hourly rate in 2026 is PLN 31.40 gross per hour. Principals cannot legally pay less than this amount for any hour worked.
What information is needed to perform an accurate salary calculation?
You need 4 pieces of data: gross or net amount, contractor status (standard, student under 26, employed elsewhere), PIT tax rate (12% or 32%), and deductible cost percentage (20% standard or 50% copyright).
Does voluntary sickness insurance change net pay?
Yes. Sickness insurance (2.45%) reduces net take-home pay by PLN 24.50 per PLN 1,000 gross, but gives access to paid sick leave (L4) and maternity allowances from ZUS.
Can I calculate salary directly from hourly rate and hours worked?
Yes, our calculator includes a dedicated hourly rate converter. Simply enter your hourly rate and total hours, and it will calculate gross, ZUS, tax, and net payout.
How are multiple mandate contracts settled in Poland?
Full social security is paid on the primary contract until cumulative earnings reach minimum wage (PLN 4,806). Subsequent contracts only incur 9% health insurance.
Does the calculator display total cost to the hiring company?
Yes. The calculator shows employer surcharges including employer pension (9.76%), disability (6.50%), accident (1.67%), and Labor Fund (2.55%).
Is this calculator result an official tax settlement?
No, this is an illustrative estimation tool based on official 2026 Polish tax laws. Final annual tax reconciliation is processed via annual PIT declaration submitted to the Polish Tax Administration.
Baza Wiedzy & Poradniki
Popularne i Aktualne Poradniki
Praktyczna wiedza, analizy przepisów 2026, interpretacje ZUS i porady ekspertów dotyczące umów zlecenia.
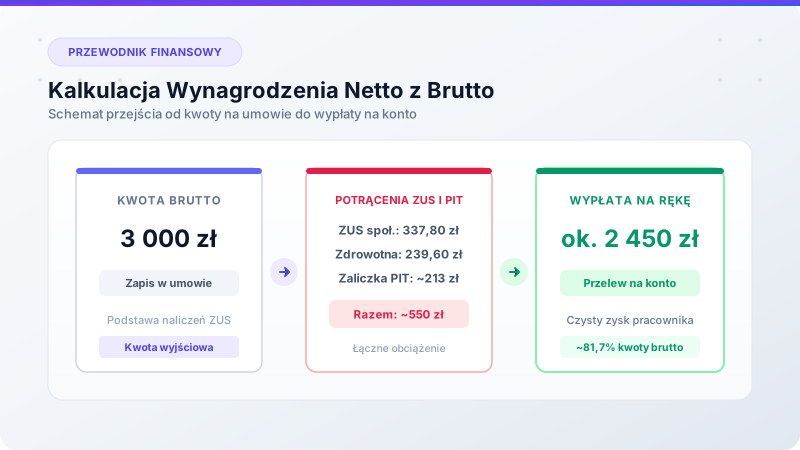
Otwierasz rachunek do umowy i widzisz kwotę wynagrodzenie brutto, ale zastanawiasz się, ile faktycznie trafi na konto. Ten przewodnik pokazuje krok po kroku, jak przejść od brutto do kwoty na rękę.
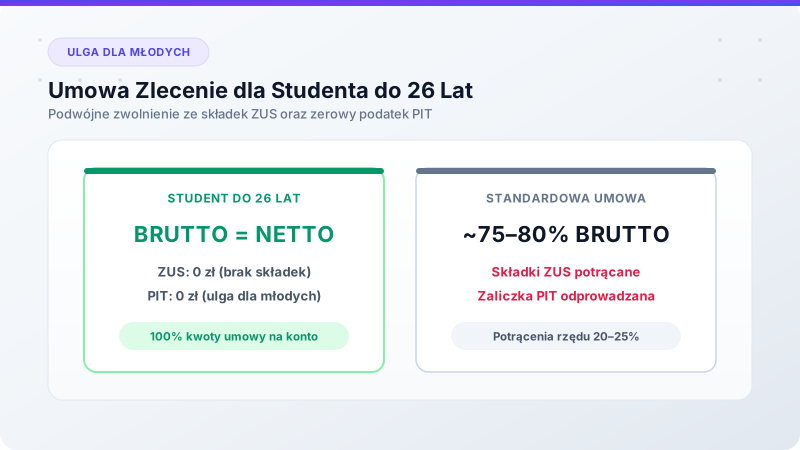
Bycie studentem ma swoje finansowe plusy, szczególnie przy podpisywaniu umowy zlecenia. Dzięki uldze dla młodych i zwolnieniu ze składek, wynagrodzenie brutto może równać się wynagrodzeniu netto.
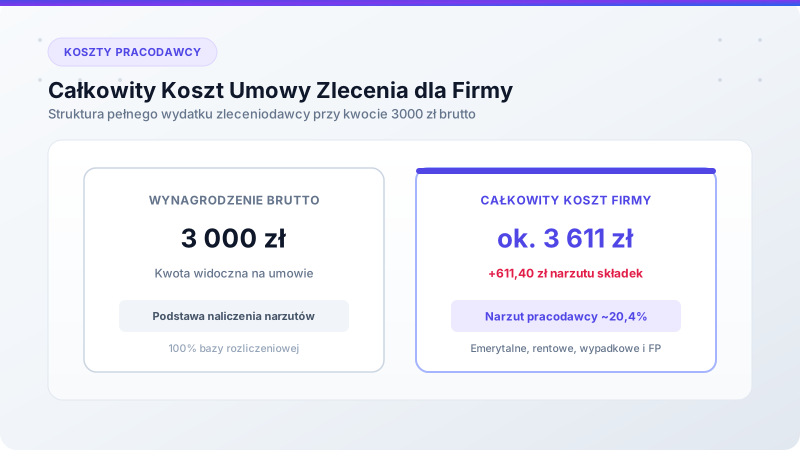
Kwota wynagrodzenia brutto to nie wszystko, co płaci firma. Zleceniodawca ponosi dodatkowe koszty pracodawcy, wynikające ze składek finansowanych po jego stronie.
 Rozliczenia i Podatki